

Welcome to my newsletter, where I share my efforts to understand markets and the world around me.
I appreciate you taking the time to read this. I love getting feedback; feel free to drop me a line. It’s great to start conversations.
Today is Thursday, the 26th of February, the 57th day of the year. There are 308 days remaining until the year’s end. On this day in 1852, an English troop carrier, the Birkenhead, under Captain Robert Salmond, stranded on a reef close to what has become known as Hermanus today.
Survivors of the wreck settled there, existing on gardening and what the sea could offer. Today, Hermanus is South Africa’s premier summer holiday destination.
How times change!
What has also changed is the software of our society, the intangible infrastructure that drives our behaviour.
Our culture.
As the Birkenhead was sinking, seven women and thirteen children were helped into the only two lifeboats available while the men stood in line on deck. The Birkenhead secured a place in history due to the gallantry of her men, who, in the face of great danger, allowed the women and children to escape in the boats before trying to save themselves by swimming ashore. Of the 638 passengers, 445 men perished.
Imagine what would happen if a contingent of our country’s armed forces found themselves in a similar position today.
How times change!
In this regard, Edelweiss Holdings plc Chairman Tony Deden recently wrote a typically brilliant essay on “the hollowing out of democratic substance beneath the preservation of democratic form”, stating: “What is emerging is not simply illiberalism imposed from above, nor a relapse into overt authoritarianism. Rather, it is a gradual reorientation of democratic politics away from restraint and toward consumption – of capital, of institutional credibility, and of social trust.”
Another way of thinking about credibility and trust is to say that they are markers of a strong culture. Credibility is only obtained through the imprimatur conveyed by years of consistently applied effort. But not just any effort – effort that moves society forward. Trust is also only obtained through consistency, both in good times and bad.
High levels of credibility and strong bonds of trust develop slowly over long periods of time. This gradual accumulation underpins the culture of a society.
In a recent issue of Big Think, Beatrice Erkers published an op-ed entitled “Why culture may be our most powerful lever for progress”. Erkers posits that culture is the infrastructure of human intelligence: “We usually think of infrastructure as bridges, satellites, and fibre-optic cables,” she writes. “But beneath steel and concrete lies something less tangible but just as powerful: culture – the stories and symbols that make some futures seem absurd, others inevitable, and a few worth building.”
Prosperity and standards of living are the downstream consequences of previous investments into its physical and cultural infrastructure. We can’t help but notice the capital investments in physical infrastructure. But the intangible investment into our cultural infrastructure is just as real and just as important. The stories we tell each other, the memes that define the principles to which we collectively subscribe. These are attributes which build and develop over time, that move us forward as a society.
Just like the level of physical infrastructure is an indicator of economic success and progress, I believe the key to a successful investment program is its underlying philosophy and process. The philosophy tells you how the investor thinks about the world, and the process tells you how she will implement this philosophy in the portfolio. To develop an advantageous philosophy and process requires an enormous investment of time and energy.
But these physical characteristics of an investment programme – its philosophy and process – are a necessary, but not sufficient condition for investment success. What brings sufficiency is a deliberate investment in the culture of the programme. If your investment manager doesn’t act consistently in both tough times and good, or if they lack intellectual integrity, or if the stories they tell don’t stack up with what is happening, eventually even the most well-developed investment process will not succeed.
Culture is like when the judge delivered his verdict on whether an item was indeed pornographic: “I know when I see it“. A strong culture replicates automatically and kicks out those who don’t fit. It is very much a self-perpetuating system. An investment programme with a strong culture is fractal – a single element/person is representative of the whole system. The companies with strong cultures I have worked at, or with – Investec, RMB or Allan Gray – were like that. By interacting with one of their employees, you could tell a lot about their firm.
But like any physical asset, culture needs continuous maintenance. Even firms with a strong culture can slip if they aren’t spending enough time and energy on it.
I wrote about the value of maintenance in “Making it Last“. My conclusions were:
“Societies characterised by trust and resilience are ones in which it pays to build – build businesses that employ more people, build infrastructure that keeps the wheels turning. The first step towards creating such a society is to take care of what is already there. To create a foundation for growth, we should first celebrate maintenance and upkeep.”
Trust and credibility define the culture of a good investment programme. The question any investor needs to ask themselves is: am I investing enough into the maintenance and upkeep of culture to ensure that it doesn’t get consumed, but sustains and strengthens?
In The Markets
1. The fat pill is working
The use of the so-called fat pill, or the class of drugs known as GLP-1, is becoming increasingly socially acceptable. GLP-1 (Glucagon-Like Peptide-1) is a natural hormone produced in the gut after eating. It regulates blood sugar, slows digestion, and signals fullness to the brain. As a medication, it mimics this hormone to effectively treat type 2 diabetes and promote weight loss by reducing appetite.
As time goes by, doctors are discovering that it has several positive side effects. These “unexpected” benefits include reduced systemic inflammation, metabolic and cardiovascular improvements, improved kidney and liver disease management, improved cognitive health, and reduced addiction and craving.
It’s no wonder that the penetration of this class of drug has grown over the past few years. In the USA, which currently has over 50% of the global market, usage has increased exponentially. By late 2025, GLP-1 prescriptions accounted for over 7% of all prescriptions in the US, up from a fraction of that in previous years.
Novo-Nordisk was first to the market with injectable Wegovy, initially leading the breakthrough in obesity medication in 2021. Despite much excitement at the time, their initial market leadership has not translated into good returns for shareholders:
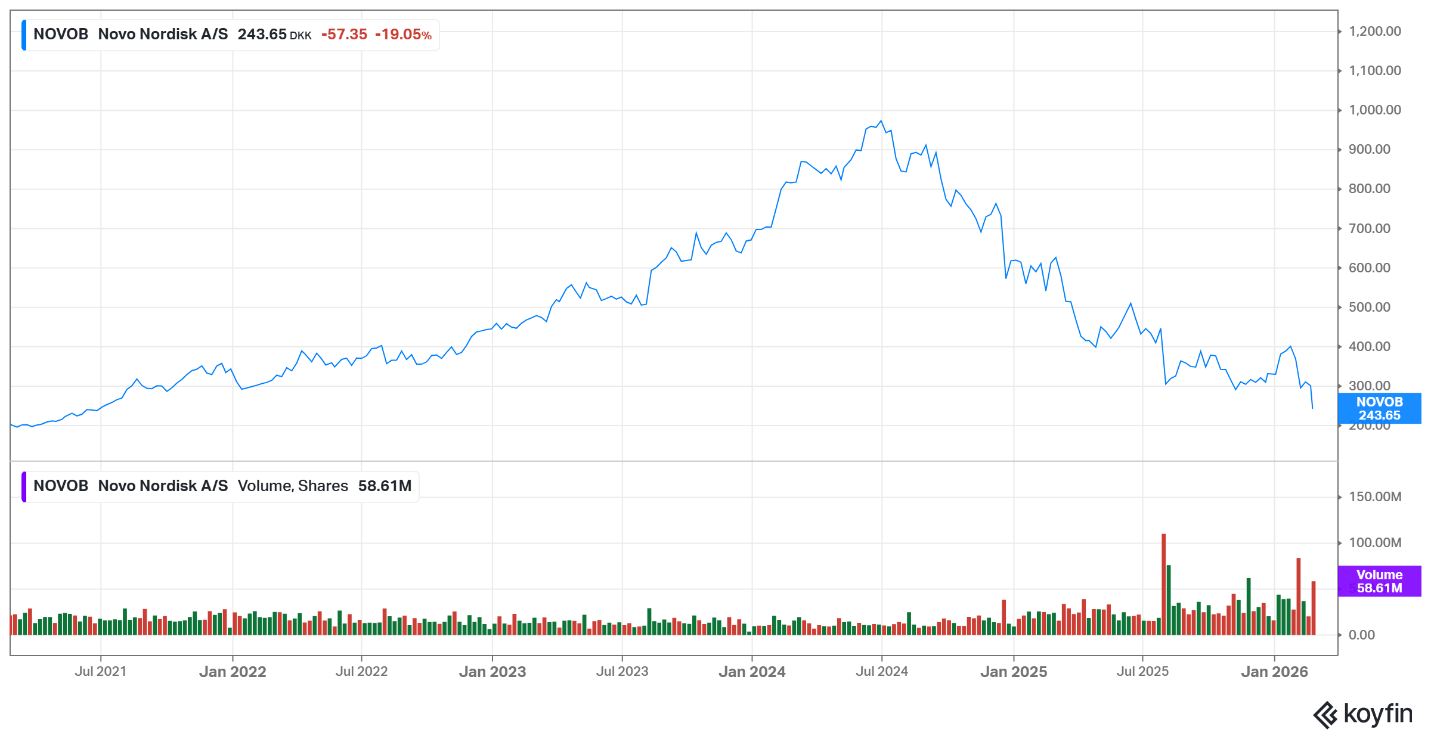
I wrote about Novo-Nordisk in 2023, at the height of the excitement about their drug, in “Bear Baiting”.
Right now, the market has shifted its excitement to Eli Lilly, which was first to market with an ingestible pill. This has expanded the addressable market, as many people don’t like to inject themselves:
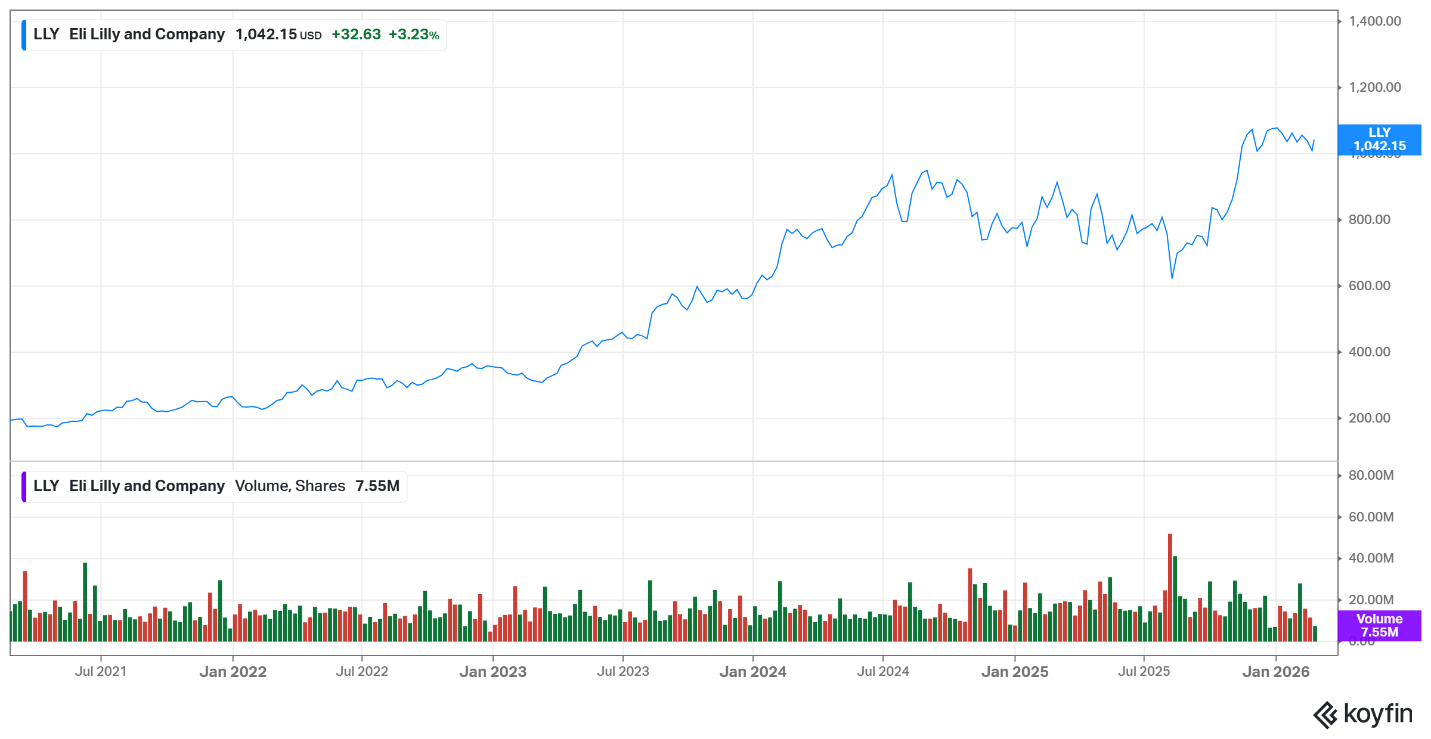
Warren Buffett famously said, “Beware of excitement and expenses, as they are the enemy of the rational investor.” Investors in Novo Nordisk would probably agree wholeheartedly with him on this point. On the other hand, Eli Lilly investors probably regard Buffett as a 95-year-old fuddy-duddy.
However, if you accept that 95 years of investment experience is worth listening to, how does one approach the investment landscape with respect to the increasing usage of GLP-1 drugs?
My approach would be to invert. Stop looking for the “exciting” opportunities and think about what to avoid. Top of my list would be the makers of snacks and beverages like Pepsico. Here’s a chart showing their volume growth:
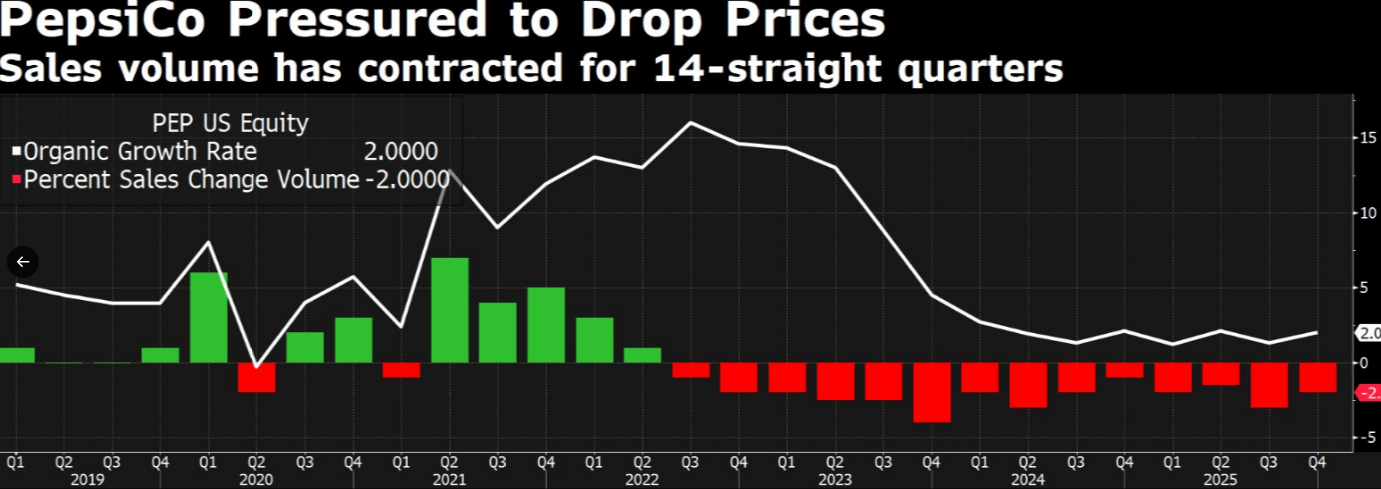
The same is happening in the alcohol industry. In January, the US Treasury released information that whiskey distillers had produced a little under 142 million combined proof gallons, which was 55 million less than a year before, as first reported by the Lexington Herald-Leader.
These are severe headwinds for future profitability. And the shareholders of drinks companies are noticing it. Here is Treasury Wine Estates, the Australian-based global maker and distributor of wines:
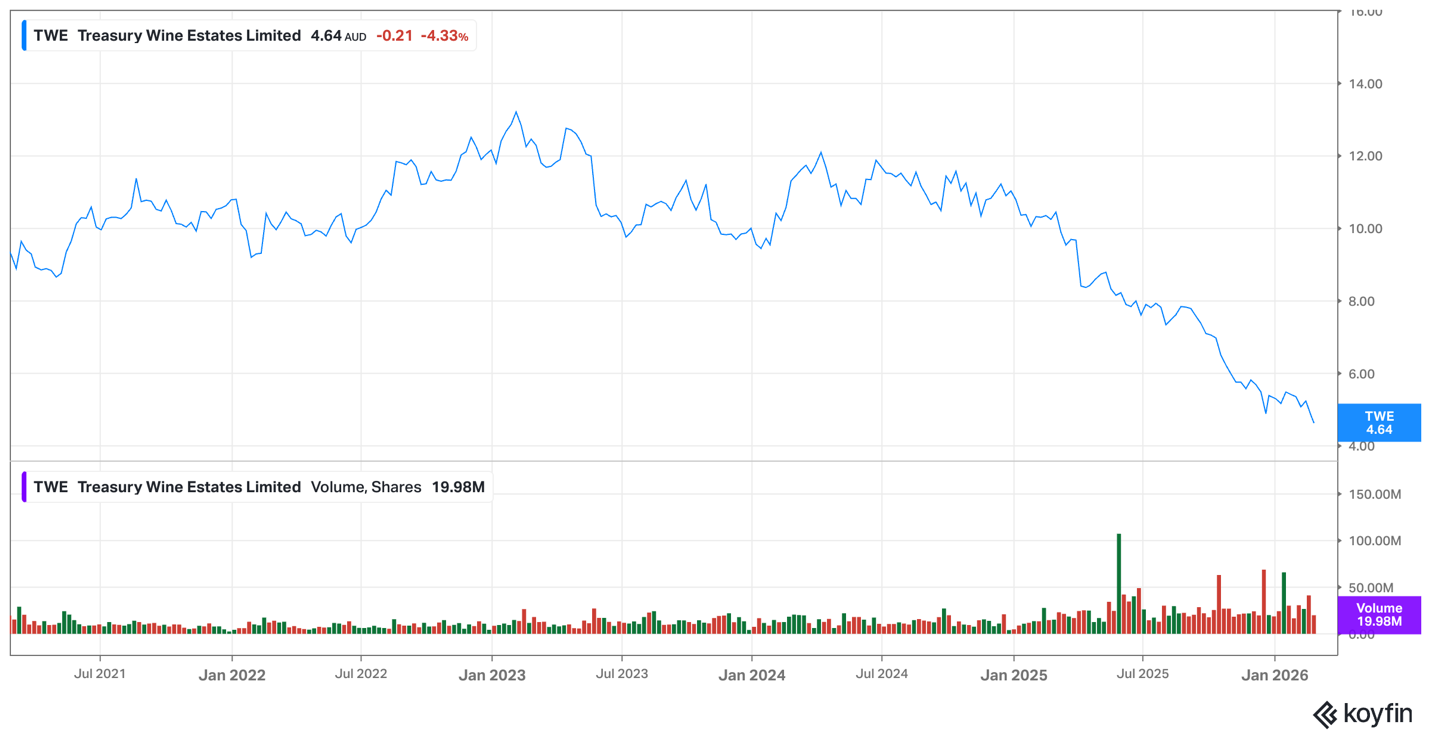
And here is the share price of Diageo, the British-based, multinational leader in premium drinks, including Johnnie Walker, Guinness, and Smirnoff:
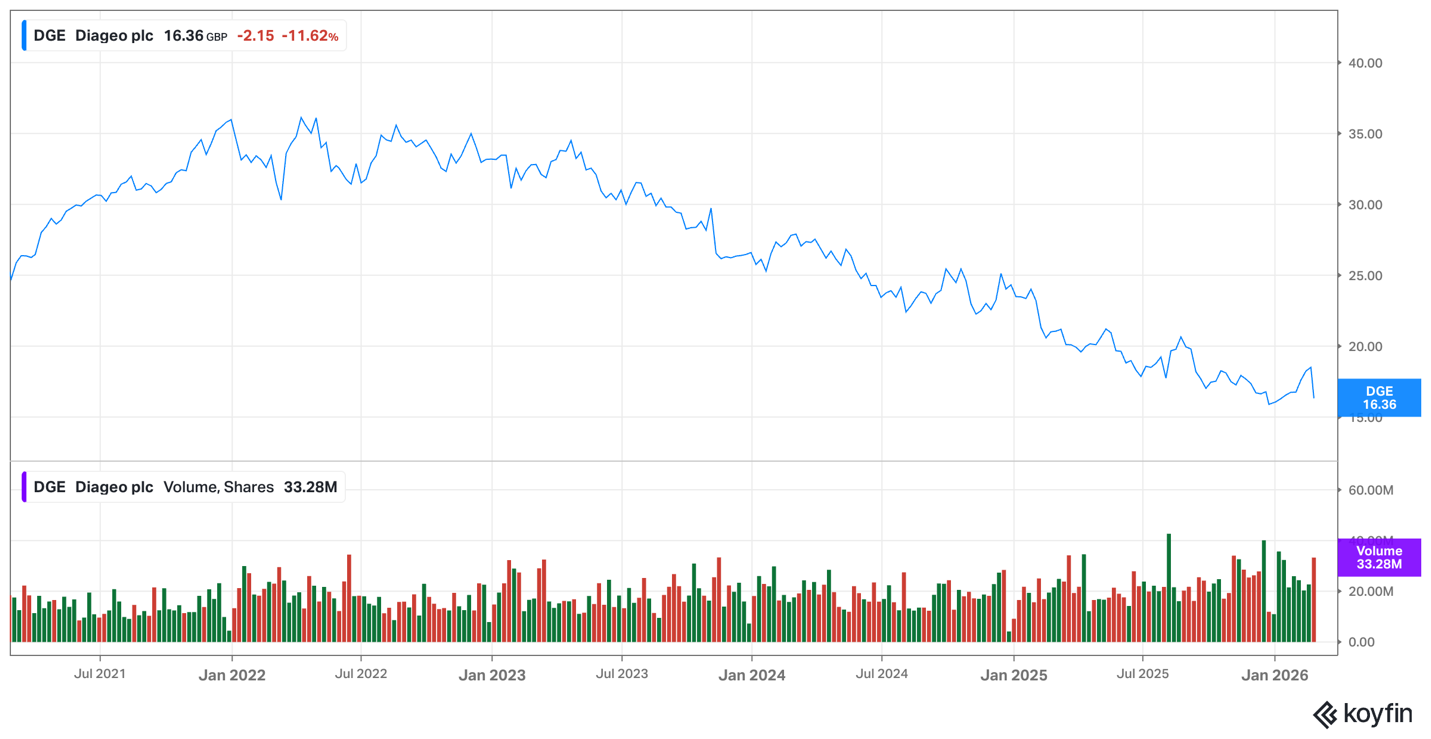
My take: An old saying in the market goes like this: “Don’t try to catch a falling knife”. These kinds of sayings are based on decades of accumulated market experience of millions of investors. In my view, that’s better than AI…
2. The sanctions are not working
When the West first introduced sanctions in Russia, media outlets reported that the “Ruble is Rubble” and that sanctions on oil would “hit them where it hurts”. So, let’s check in with Russia and see how it’s going.
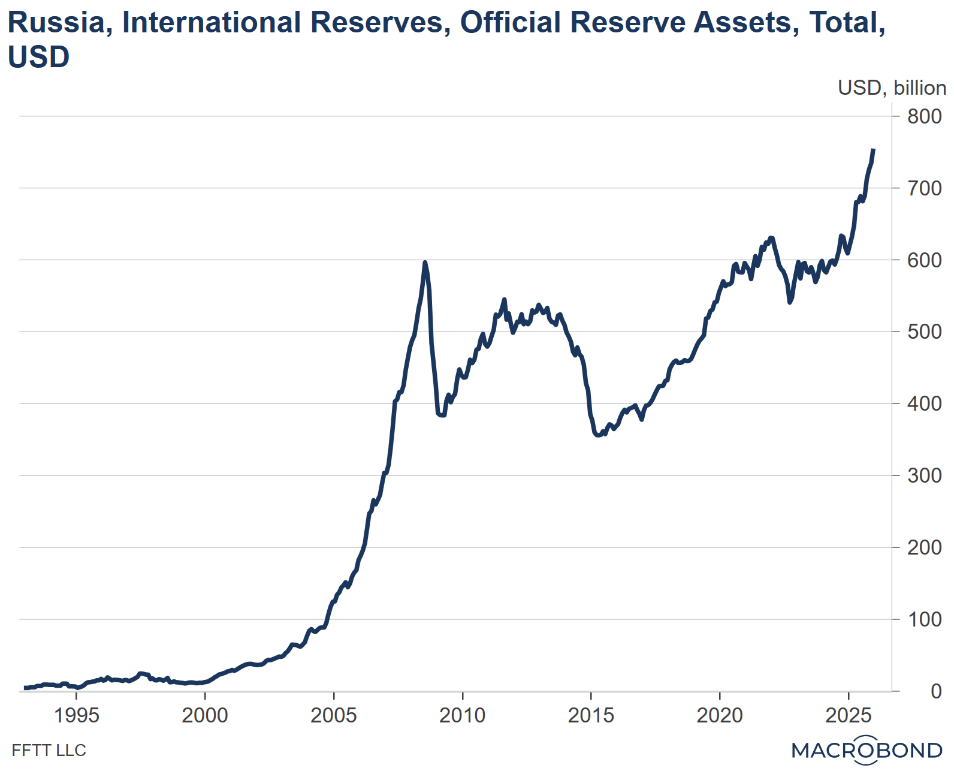
Here are Russia’s foreign reserves:
And here’s the Russian ruble against the US dollar:

Since the start of the Ukraine war and the subsequent inception of Western sanctions, Russia’s foreign reserves have increased, and the Ruble has strengthened!
What’s going on?
As a result of sanctions, India and China get to import cheap oil from Russia – a nice gain for them. But Russia continues to earn foreign exchange. On top of that, Russia historically held a large proportion of its reserves in gold, which is no one else’s liability and cannot be sanctioned. I don’t have to tell you what has happened to the gold price over the past few years.
Russia’s gold holdings mean that despite fighting an expensive war, being cut off from the western financial system, and the West seizing hundreds of billions of dollars of Russian forex reserves, its reserves are at an all-time high. How so? Essentially, the West printed money to pay for its side of the war, bidding up Russia’s gold and, by extension, Russia’s FX reserves!
My take: If Russia, India and China are all better off due to sanctions, who is paying the bill? My guess is that the taxpayers in the West will be first in line to find out.
3. King Code Contortions
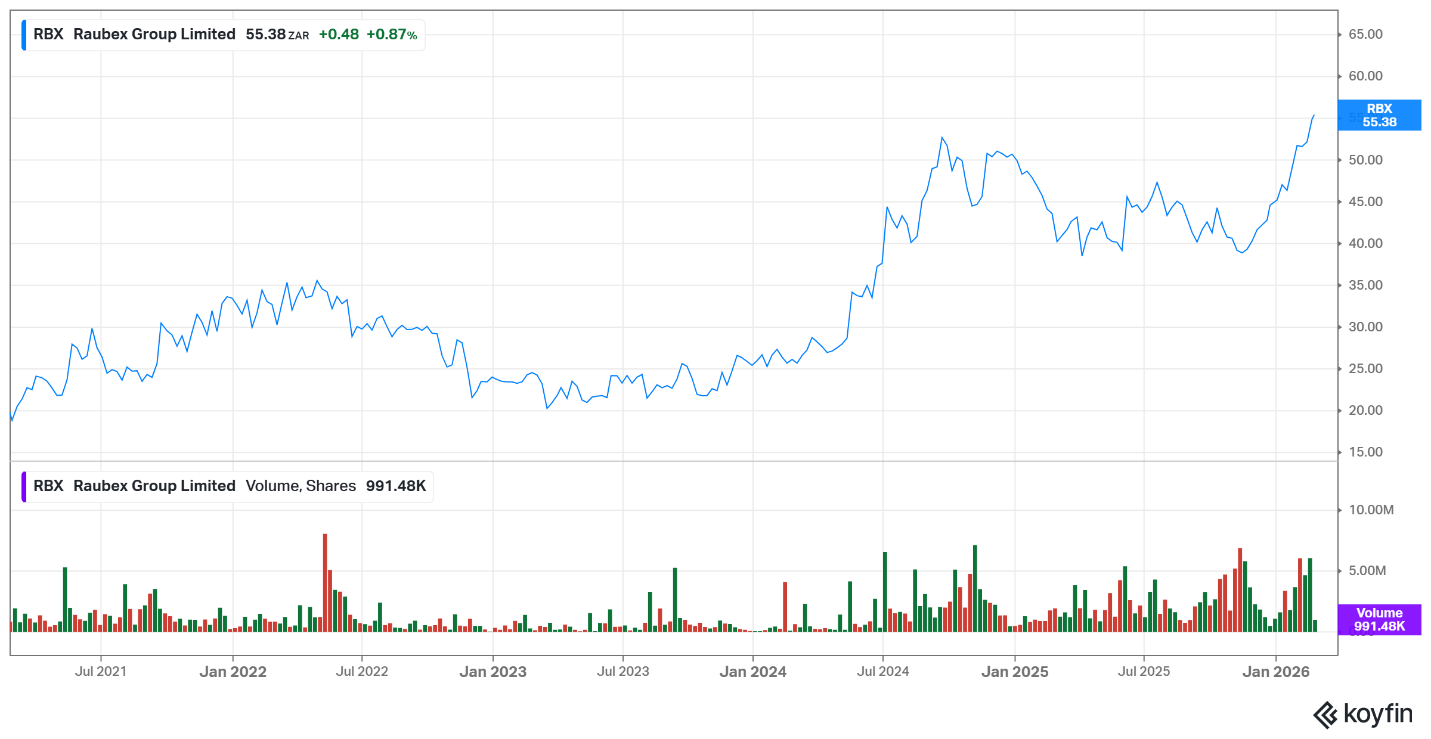
This week, local mining and construction company Raubex released an interesting stock exchange announcement. In it, they said: “Louis Raubenheimer, son of founder Koos Raubenheimer, has been appointed to the board of that company as an independent non-executive director. He has extensive prior experience with the company, having held various roles from 1992 to 2022. His most recent role was running the Roads and Earthworks Division”.
So, let me get this straight. The son of the founder, who also worked at the business for 30 years, and whose family wealth is most likely tied to the business’ prospects, is “independent”? Apparently, in terms of the nonsensical King code, he is.
My view would be very different, but then again, I am no corporate governance expert.
However, I also believe this is a good appointment. Mr Raubenheimer clearly knows the business well and has skin in the game – both of which are positive attributes for a director who needs to look after shareholders’ interests.
My take: I don’t care whether the King code regards Mr Raubenheimer as independent or not. As a shareholder, I welcome his addition to the board. The market also seems to like it:
4. Turn, turn, turn
Pete Seeger wrote the famous song, “Turn, Turn, Turn”, which was made famous by the Byrds. Here’s a sample of the lyrics:
To everything, turn, turn, turn
There is a season, turn, turn, turn
And a time to every purpose, under heaven
A time to build up, a time to break down
A time to dance, a time to mourn
A time to cast away stones
A time to gather stones together
To everything, turn, turn, turn
There is a season, turn, turn, turn
And a time to every purpose under heaven
They could have been singing about the South African food retail sector, where we have two large companies trying to turn their fortunes around: Pick ‘n Pay, which I wrote about last week, now also joined by Spar. Both companies are, unsurprisingly, struggling with revenue growth as they must cut prices to maintain market share.
Both their share prices are in the tank, with value investors circling. Here’s Spar:

Spar’s forward P/E of less than 9 is at its lowest level ever.
And here’s the Pick ‘n Pay share price, almost three years into their turnaround
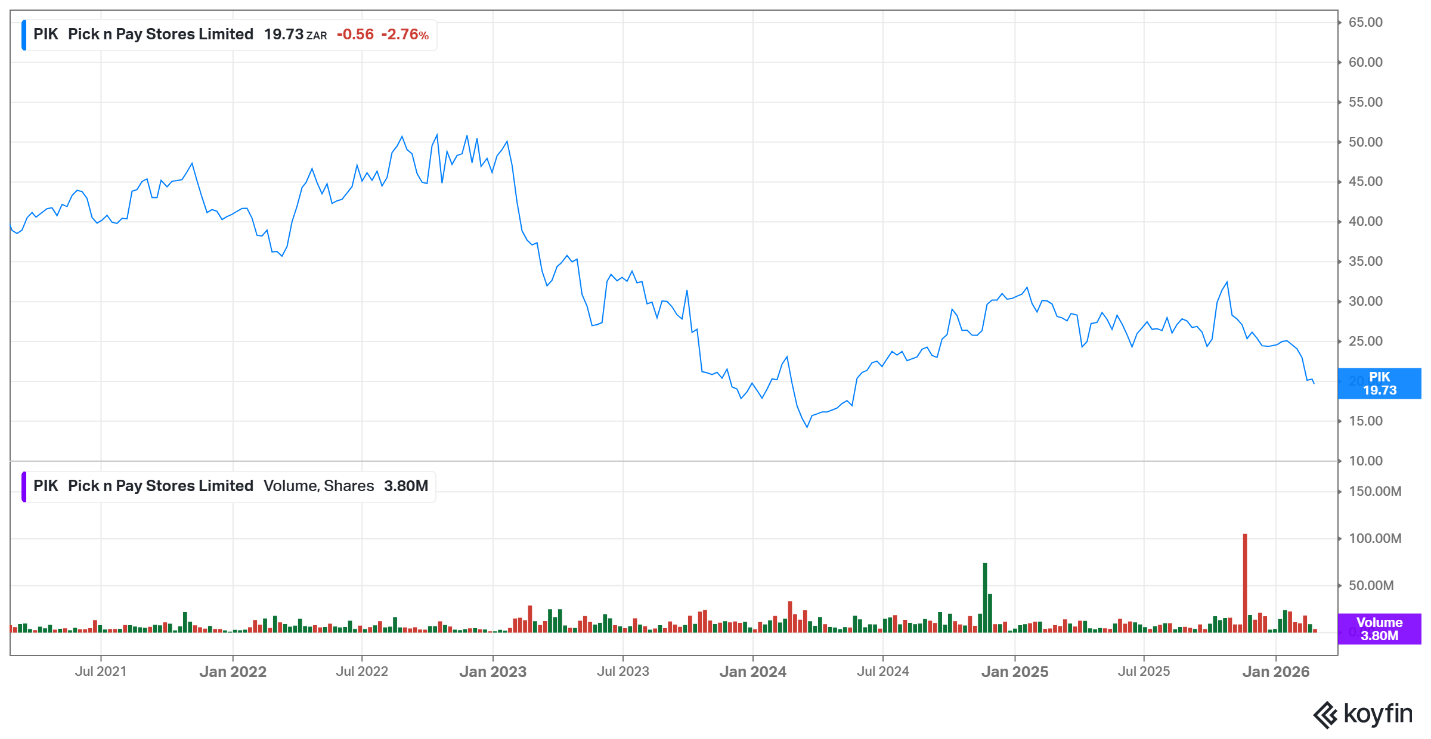
In fact, stripping out Pick ‘n Pay’s holding of Boxer shares, the market is placing a negative value on the core businesses. Which, it might be added, continues to lose money.
It’s no surprise the value guys are interested. But I would be cautious here. Shoprite is the behemoth in the sector, and if it starts playing the discounting game from its position of strength, things could get ugly out there.
My take: Turnarounds are super difficult. I think I have said this before, but I would only invest in a turnaround if these three requirements were met:
- A “kitchen-sinking” of the accounting.
- Under new management.
- Complete disinterest from the market.
Neither Spar nor Pick ‘n Pay qualify yet, considering the third criterion.
5. Thank you, Nimby’s!
I have often written about one of my favourite companies in the world, Texas Pacific Land. In my opinion, it is the ultimate real asset. Operating margins of 75%, RoEs of 40%, and almost no capex. A P/E of 75 is not high for this type of business, especially if you look at its history.

What does it do? It simply owns land in West Texas – home to the Permian Basin, the largest oil and gas basin in the USA. It generates revenue through oil and gas royalties, water services (sourcing, disposal, recycling) for fracking, and land surface easements. It’s one of the core holdings in the “Hard Asset” portion of the MWI Worldwide Flexible Fund (aka The Cockroach).
In a recent newsletter, Scott Galloway (Prof G) asked: “What if most Americans decide they don’t want a data centre in their backyard? If that happens, what would it do to Google’s or OpenAI’s future cash flow? Does that hurt future revenue growth? I would argue yes.”
On the other hand, TPL recently invested in Bolt Data & Energy, describing Bolt as “a new AI infrastructure platform chaired by former Google CEO, Eric Schmidt.” TPL retains the right of first refusal to provide water to Bolt-affiliated projects and is working on several data centre developments.
The TPL share price liked this news:
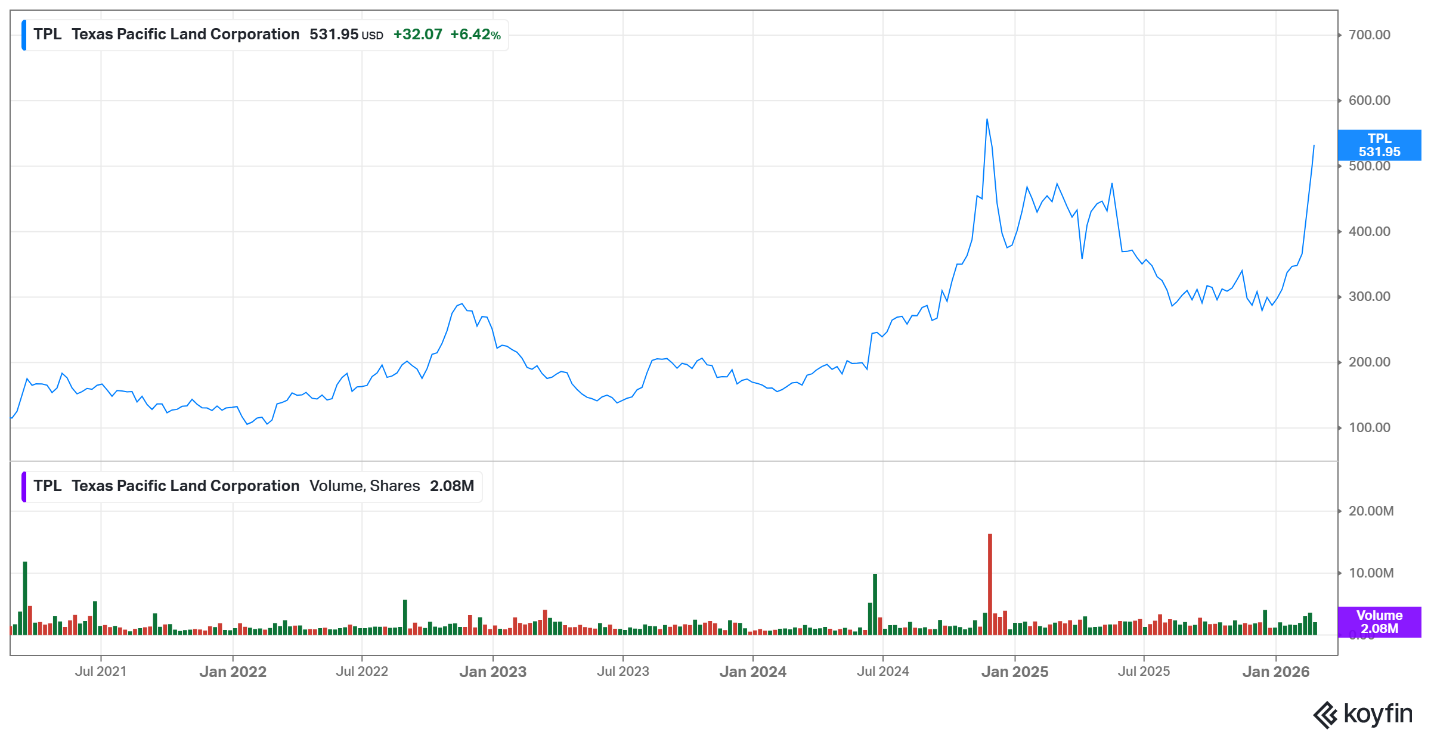
My take: I would take the other side of Prof G’s argument. Data centres will simply move from urban centres to Texas, where energy is cheap, and no one lives. And it’s busy happening.
In the cockroach
I was going to discuss the individual holdings of the equity portion of the fund* this week, but I had to do some trades, so I am going to postpone the equity discussion to next week.
Driven mainly by its holding of physical gold, the hard asset portion of the portfolio has done well. As a result, the weight of this portion of the fund increased to 27.5%, well above its 25% target. At the same time, this meant the cash, bond, and equity portions of the fund declined below their individual targets for 25% each.
This forced me to do some transactions, as follows:
I sold Yellow Cake (a London-listed investment trust that has as its only holding U3O8 or uranium – colloquially known as Yellow Cake) from 3.3% down to 0.8%. Uranium has had a strong run, and the fund has a decent allocation to energy via Texas Pacific Land, FRMO, and XLE (the energy sector ETF). Together they make up 7.5% of the fund, or almost a third of the hard asset allocation.
From the proceeds of this sale, I did the following trades:
- Add 0.6% to the Japanese Yen deposit, taking it to 4% of the fund, and the overall cash allocation from 24.4% to 25%.
- Add 0.8% to 2561 JP (the Japanese bond ETF), taking it from 4.2% of the fund to 5%; and taking the overall bond exposure from 24.2% to 25% of the fund.
- Add 0.4% to LSEG, taking it back up to 2.5% of the fund. LSEG is one of the cheapest exchanges worldwide and has recently suffered an AI-related sell-off. Activist Elliot has taken a stake, which could be a catalyst. Notwithstanding that short-term phenomenon, LSEG is one of my 10 stocks forever, and I like to add to them when I can.
- Despite that, I am not looking to increase any of the other existing positions in the “10 stocks forever” holdings (Berkshire, DSM-Firmenich, Nestle, or Disney). Nor do I want to buy any of the other five (Mastercard, Hermes/Ferrari, Apple/Microsoft, Nintendo/Roblox, Investor AB) right now. The market action looks quite weak, and I think a better opportunity will come up in the next 12-36 months. So, in the meantime, to get the equity exposure back up to 25%, I added 0.7% to EIMI LN, the iShares Emerging Markets ETF, bringing it to 6.1%.
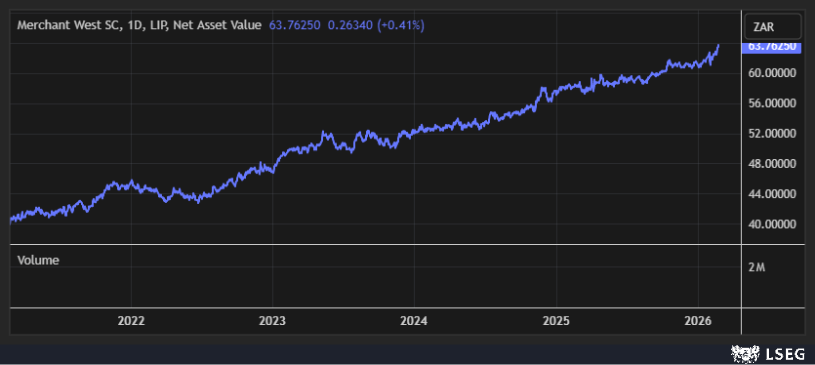
Overall, the cockroach continues to chug along nicely, reaching new all-time highs in Rand terms this week:
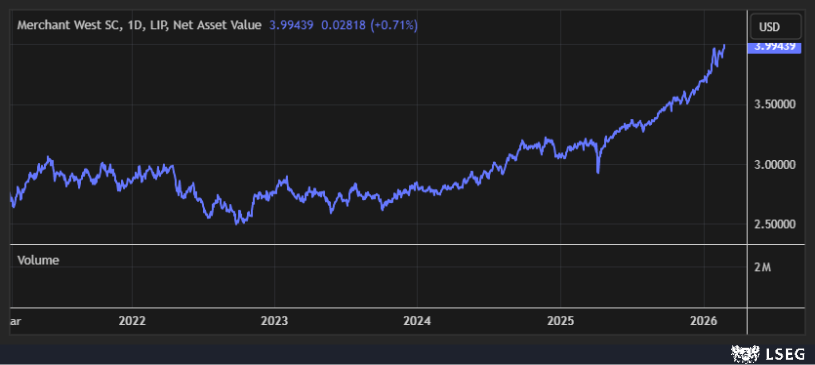
As well as in US$ terms:
* I manage the fund on behalf of Merchant West Investments (Pty) Ltd (FSP 44508)
In The Media
1. The history of Sasol
Here’s a neat video discussing Sasol’s history from its origins during apartheid South Africa to its eventual near-collapse under an American CEO. As turnarounds go, this one ticks all three boxes I mentioned earlier. But I thought the history is fascinating, even from the viewpoint of a non-investor. Which, in terms of Sasol, most people are these days.
You can watch it here; it’s only about 30 minutes long.
2. The best music of 1999
Remember 1999? The year of Y2K, when all companies had to certify in their accounts that they were Y2K-compatible. There was a real fear that when the calendar changed from 31 December 1999 to 1 January 2000, planes would fall out of the sky, elevators would drop uncontrollably, and machines would generally go wonky. All because it was thought that programmers had forgotten to take account of the change of century in their code.
A widely believed rumour was that you had to completely shut down your PC at 11:59 p.m. to stop it from “exploding” or crashing. Some extremist groups claimed the Y2K bug was a biblical sign of the end times, leading to apocalyptic predictions. These were, of course, promptly debunked once the new year began peacefully.
The situation was hilarious. At the same time as the Y2K hysteria, there was a huge bubble happening in so-called TMT (technology, media, and telecommunications) stocks. It was the dawn of the internet, and anything with a dot.com label was being bid up to the sky. All while being fearful that a simple change of date would bring everything crashing down together.
Talk about being able to hold two incompatible ideas in your head at the same time…
But the music was exceptional!
Here is a list of the best albums of the year, on Apple Music and on Spotify.
And here is a list of the top 20 songs of the year, on Apple Music and on Spotify. Once again, ranked from nr 20 to nr 1.
Finally, here is a long list of all the best songs of the year, only on Apple Music.
I have to say, without singling out any artists – like Wilco, Fiona Apple, Joe Strummer, Live – 1999 was a great year for music. And who remembers “Blue Eyes” by The Springbok Nude Girls? What a year!
That’s all for this week. Remember, be careful out there.
Piet Viljoen
RECM
26 February 2026